
Looks like you're visiting from {country}...
Switch to our {language} site for local pricing and products
Merchant insights
What is cash flow, and how can you manage it effectively as a small business owner?
IN THIS ARTICLE
This is a div block with a Webflow interaction that will be triggered when the heading is in the view.

The movement of money going in and out of a business in a specific period of time, is called cash flow. And cash flow in itself is all about timing. Your small business can be making sales and still run short of money if customer payments arrive after rent, wages or supplier bills are due.
For a coffee shop, kiosk, restaurant or even a retail shop, such as a bookshop, keeping track of what is coming in and what needs to go out is a basic part of staying in control day to day.
In this guide we’ll explain what cash flow means, how it differs from profit and what small businesses can do to manage it more effectively.
Key takeaways:
- Cash flow is the movement of money into and out of a business over a given period, and it is different from profit.
- Positive cash flow means more money is coming in than going out, while negative cash flow means more is leaving the business than coming in.
- Cash flow problems for small business can arise even when the business is profitable, particularly when incoming and outgoing payments do not line up.
- Tracking daily cash flow and planning ahead for quieter periods can make it easier to cover bills and avoid unexpected pressure on the business.
What is cash flow?
Cash flow is the movement of money into and out of a business over a set period, such as a day, week or month. Money coming in from sales, financing or other income is known as a cash inflow. Money going out to cover rent, wages, stock, supplier invoices and other costs is a cash outflow.
The difference between the two is your net cash flow for that period.
Cash flow and profit are closely related, but they are not exactly the same thing. A business can be profitable overall and still run into cash flow problems for small business operations if money is not arriving at the same time bills need to be paid.
For example, a customer paying a large invoice 60 days late or a retailer paying upfront for seasonal stock can create a temporary cash flow gap, even when the business is performing well overall.
Why is cash flow more important than profit on its own?
Profit is measured over a period, such as a month, quarter or year, and can include income and costs that have not yet been received or paid. Cash flow is more immediate than that. It shows whether the business has enough money available to cover its outgoings when they fall due.
That is why understanding cash flow vs profit matters for small business owners is important. A restaurant might show a healthy profit over the year, but if wages are due on Friday and expected takings have not reached the bank account yet, that profit figure does not solve the first occurring problem.
A profitable business can still come under pressure if cash is tied up or arrives too late. So, keeping an eye on both profit and cash flow gives a much clearer picture of how healthy your business really is.
Let’s take a further look into the two types of cash flows.
Positive vs negative cash flow
Positive cash flow means more money is coming into the business than going out over a given period. This can give a business more room to pay bills on time, invest in stock or build a buffer for quieter months.
Negative cash flow means more money is leaving the business than coming in. Remember, that is not always a problem. A business might deliberately spend more for a short period when investing in equipment, opening a new location or stocking up ahead of a busy season.
The concern comes when negative cash flow continues without a clear plan for bringing more money in or reducing outgoings.
Tracking positive and negative cash flow trends over several months can help you spot recurring pressure points, understand seasonal patterns and see whether your business is building or using up its cash reserves over time.
Common causes of cash flow problems
Cash flow problems often come down to timing, planning or money being tied up where the business cannot use it immediately.
We’ve listed the most common causes below:
- Slow-paying customers, especially in businesses that invoice rather than take payment immediately. Late customer payments can create a long gap between completing the work and actually receiving the money.
- Seasonal cash flow for small businesses, where revenue is concentrated in certain months while costs continue throughout the year. A seaside café, for example, may earn most of its income during the summer but still face rent and other fixed costs in winter.
- Overstocking ahead of demand that does not materialise, leaving cash tied up in products sitting on shelves.
- Underestimating regular outgoings such as rent, insurance, utilities or loan repayments when planning for quieter periods.
- Rapid growth, which can create cash flow strain during business growth when a business needs to spend on stock, staff or premises before the additional revenue comes in.
Spotting which of these patterns is affecting your business makes it easier to decide what needs to change, whether that means collecting payments faster, reducing stock levels or planning more carefully for seasonal costs.
How to manage cash flow effectively for your business
A few practical habits can make cash flow easier to control, especially for a small business:
- Forecast cash flow weekly or monthly rather than waiting until the end of the quarter. Mapping expected inflows and outflows can help you spot a tighter period before it arrives.
- Keep a cash flow buffer for quieter periods or unexpected costs, rather than relying on every month going exactly to plan.
- Follow up on late customer payments promptly and consistently so unpaid invoices do not build up.
- Time larger purchases, such as stock or equipment, around periods when cash flow is naturally stronger where possible.
- Review fixed vs variable costs regularly. Variable costs are often easier to adjust in the short term if cash flow starts to tighten.
It also helps to keep a clear view of daily sales. Knowing what the business is taking in makes it easier to compare actual income with upcoming bills, supplier payments and other commitments, rather than waiting until month-end to see whether your forecast was accurate.
Approaches that help with cash flow visibility
Cash flow forecasting for small businesses can be as simple as comparing expected income with upcoming costs. The better your view of daily sales, the easier it is to see whether money coming in is likely to cover wages, supplier invoices and other commitments.
This becomes even more useful when managing cash flow across multiple locations or shifts. Flatpay's POS system gives merchants a clear view of sales and transactions, which makes it easier to follow the income side of cash flow without piecing figures together manually.
For businesses like Burger Palace, which handle a high volume of orders, straightforward payments and clear pricing have also made a financial difference:
“The ease and simplicity of their platform have saved us a significant amount of money each month, which has been invaluable to our business.” - Sercan, Owner of Burger Palace.
Keeping payment costs predictable and having a clearer view of sales will not prevent every short-term cash flow gap, but both can make it easier to plan ahead and make informed decisions about what the business can afford.
FAQ
What is cash flow in simple terms?
Cash flow is the movement of money into and out of a business over a given period. It shows what money is actually coming in and what needs to go out, making timing just as important as the amounts involved.
What's the difference between cash flow and profit?
Profit shows whether a business earns more than it spends over a period, while cash flow looks at when money is actually received and paid. That is why understanding cash flow vs profit matters: a business can be profitable overall but still struggle if bills fall due before enough cash has come in.
What causes cash flow problems in small businesses?
Common causes include late customer payments, seasonal cash flow dips, overstocking, unexpected costs and rapid growth that requires spending before the additional revenue arrives.
How can a small business improve its cash flow?
Regular cash flow forecasting, keeping a cash buffer, following up on late payments and maintaining a clear view of daily sales can all help. Businesses can also review when costs fall due and whether spending can be timed more closely with expected income.
Is negative cash flow always a bad sign?
Not necessarily. A business might have negative cash flow temporarily while investing in equipment, opening a new location or building stock ahead of a busy period. The concern is when more money continues to leave the business than comes in without a clear plan for reversing the trend.
Accepting payments for any business, anytime, anywhere
Three solutions designed to get you paid.


Getting paid starts here
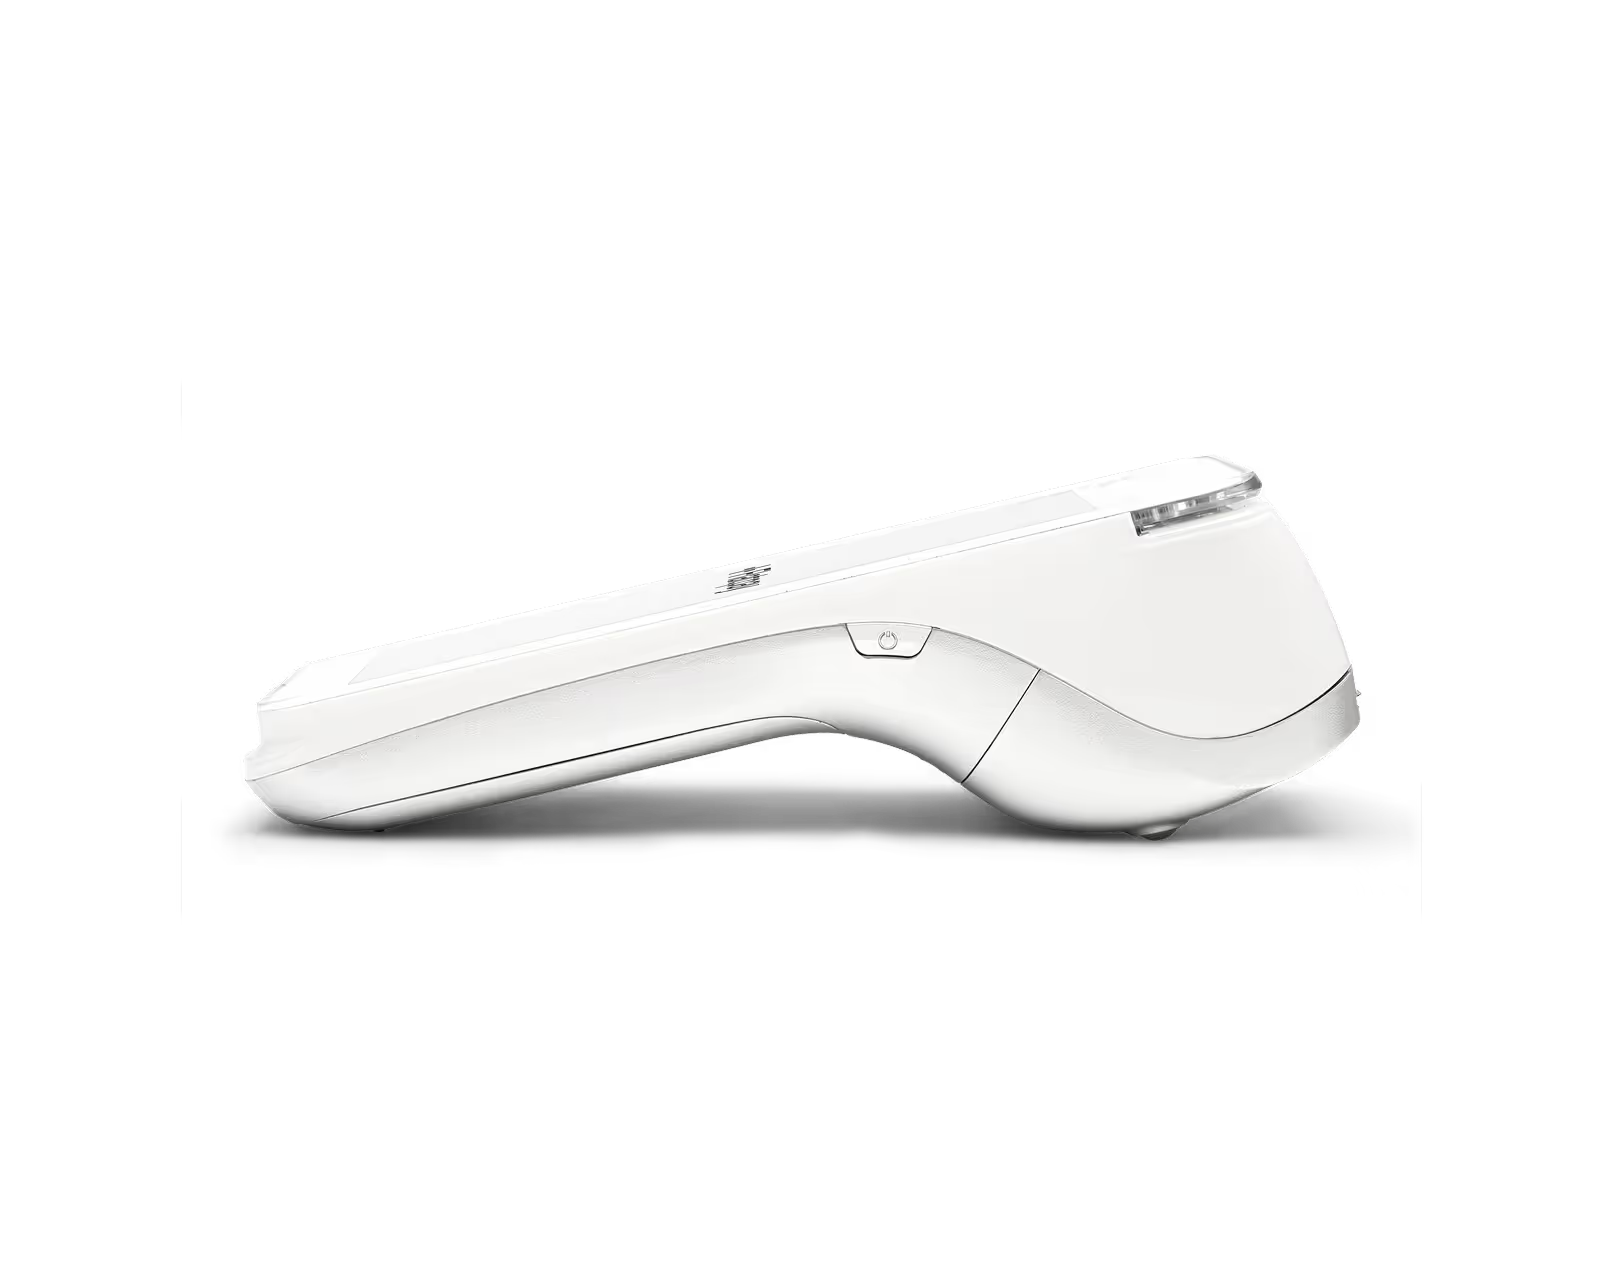
Let us get you set up to accept card payments and manage orders in one place. Get started today and see how smooth running your business can be with Flatpay.

